

THE KING BETWEEN TWO COLUMNS
To the Greeks, hubris described something more precise than ordinary vanity: a man forgetting that the edges of his own design were not the edges of the world, and then behaving as though reality itself, or the gods presiding over it, were bound to respect a line he alone had drawn. The pattern is worth keeping close at hand when examining a figure modern finance treats with almost reflexive deference: the confidence interval.
A confidence interval, read honestly, makes a fairly humble claim. Assume this particular model, this particular dataset and this particular list of assumptions, it says, and the true figure will probably sit somewhere inside a stated band. Each assumption on that list acts like a fence post, and the number inside the fence can only be trusted for as long as every post stays exactly where it was placed.
The device wears this dependency openly, printed right into its own definition, which is more than can be said for most of the people quoting the number afterward. Strip away the qualifying clauses, and a bare pair of figures is all that remains, repeated in meetings and memos long after anyone involved recalls the assumptions that made those figures meaningful in the first place.
Finance adopted its favourite statistical shape, the bell curve, for good reasons. Louis Bachelier reached for the bell curve in 1900, and finance never really put it down: by the 1970s, option pricing, portfolio construction and risk measurement across the industry had all come to assume that market returns cluster around an average in a predictable, well-behaved way, with genuinely extreme moves becoming rapidly, reliably rarer the further they sit from that average. The assumption is far from foolish: it fits a great deal of ordinary trading quite well, which is precisely what let it harden, over decades, from a convenience into something closer to an article of faith.
Warnings were not entirely absent either. The mathematician Benoit Mandelbrot said as much in the 1960s, arguing that real financial markets show far fatter tails than the bell curve allows, with extreme moves occurring far more often than the standard assumption predicts; the trader and essayist Nassim Nicholas Taleb has said little else since. Their warnings were well known inside the profession long before 2007, and most working practitioners filed them away as an interesting theoretical caveat, a footnote to keep teaching alongside the model everyone kept actually using.
Trouble begins when the fence itself becomes an object of admiration. An interval computed to several decimal places, narrow and tidy and confidently printed, can carry more apparent authority than its actual foundations support: a tidy guess about how much nobody in the room actually knows, dressed up in the full formality of arithmetic. Narrowness reads as rigour. Sometimes it genuinely is. Just as often it is only the rigour of the arithmetic, applied faithfully to premises nobody has stress tested in years.
An interval removes no uncertainty from the world; at best it relocates one slice of that uncertainty into a shape you can compute with. Everything the interval reports is conditioned on the chosen model holding up, and about that larger question it has absolutely nothing to say. When the foundations underneath happen to be sound, this division of labour works perfectly well. When the assumptions underneath are mistaken, the interval keeps its exactness while losing its relevance: it measures the wrong quantity altogether, confidently and to several decimal places, which makes the resulting error harder to notice than a vaguer, more obviously uncertain number would have been.
Overreach, when it arrives, arrives politely. Nobody sits down and decides to mistake a well-formatted output for a well-founded one. It simply happens: a tidy decimal point gets read as diligence, diligence gets read as insight, and before long the printed precision of an answer carries more weight in the room than the reasoning that actually produced it. By the time anyone thinks to ask whether the underlying model deserved that much trust, the number has usually already been used to make a decision.
In August 2007, as two of Goldman Sachs’s quantitative hedge funds suffered steep losses during the early weeks of the subprime mortgage crisis, the bank’s chief financial officer, David Viniar, told the Financial Times that the funds had been seeing, in his own words, twenty five standard deviation moves, several days in a row. The admission was almost disarming in its honesty, offered at the time as an explanation for an unlucky week. Few people, in the moment, heard it as a confession that the entire risk framework had just failed a basic reality check.
Such an event, under the kind of statistical assumptions ordinarily used to build these models, is not merely rare. It is rare on a scale that has no meaningful comparison in the observed history of financial markets, or arguably in the observed history of anything; moves that extreme, under those assumptions, should not occur even once across timescales many multiples longer than the age of the universe. For several to occur in a single week leaves two honest interpretations on the table. Either the markets had produced a statistical miracle of almost theological proportions, or the model describing what a normal market move even is had been wrong from the start, and the interval built on top of it had been measuring the wrong quantity in perfect, reassuring detail the entire time.
Only the second interpretation has been taken seriously by anyone who has thought about it since. The model had assumed markets moved according to a particular statistical shape, convenient to calculate with and accurate enough in ordinary years, and its builders had gradually started treating that shape as the actual texture of reality, a serviceable approximation mistaken for the territory it was only ever meant to map. That is hubris in its oldest sense: a fence, drawn for practical reasons and tested mainly in calm weather, mistaken for the edge of the world.
Ten years earlier, two Nobel laureates in economics had already run a version of the same experiment, with better mathematics and the same ending. Long-Term Capital Management, the hedge fund in question, built its trading on models calibrated against decades of historical price relationships between different markets. In the autumn of 1998, following Russia’s default on its own debt, those relationships broke down simultaneously and in a direction the fund’s models had treated as close to impossible. The firm had to be wound down in an operation organised by the Federal Reserve and funded by a consortium of major banks, because the model’s confident fences had never been built to survive the kind of weather that actually arrived, whatever the arithmetic inside those fences had looked like on any ordinary day.
Regulators and risk managers now have a name for this specific failure: model risk, the danger that a model is internally consistent, carefully calibrated, and simply wrong about the world it claims to describe. Serious institutions maintain model validation teams whose entire job is to stress a model against scenarios its own assumptions consider nearly impossible, precisely because a model, unlike a bridge, gives no visible sign of strain before it fails. Reverse stress testing, in particular, works backward from a catastrophic outcome and asks what combination of assumptions would have to break for that outcome to occur, a deliberately uncomfortable question to keep asking of a model everyone otherwise trusts. A bridge groans under a load it cannot bear. A pricing model simply keeps printing a tight, elegant number until the day it is spectacularly wrong.
Nemesis is the Greek word for what tends to follow hubris: the gap between the boundary a man drew and the boundary that was actually there, finally becoming visible, usually all at once and at the worst possible time. Markets rarely announce a correction in advance. They tend to arrive in the same two stages regardless: a long period in which the fence gets mistaken for the edge of the world, followed by a short, violent period in which that mistake stops being possible to sustain.
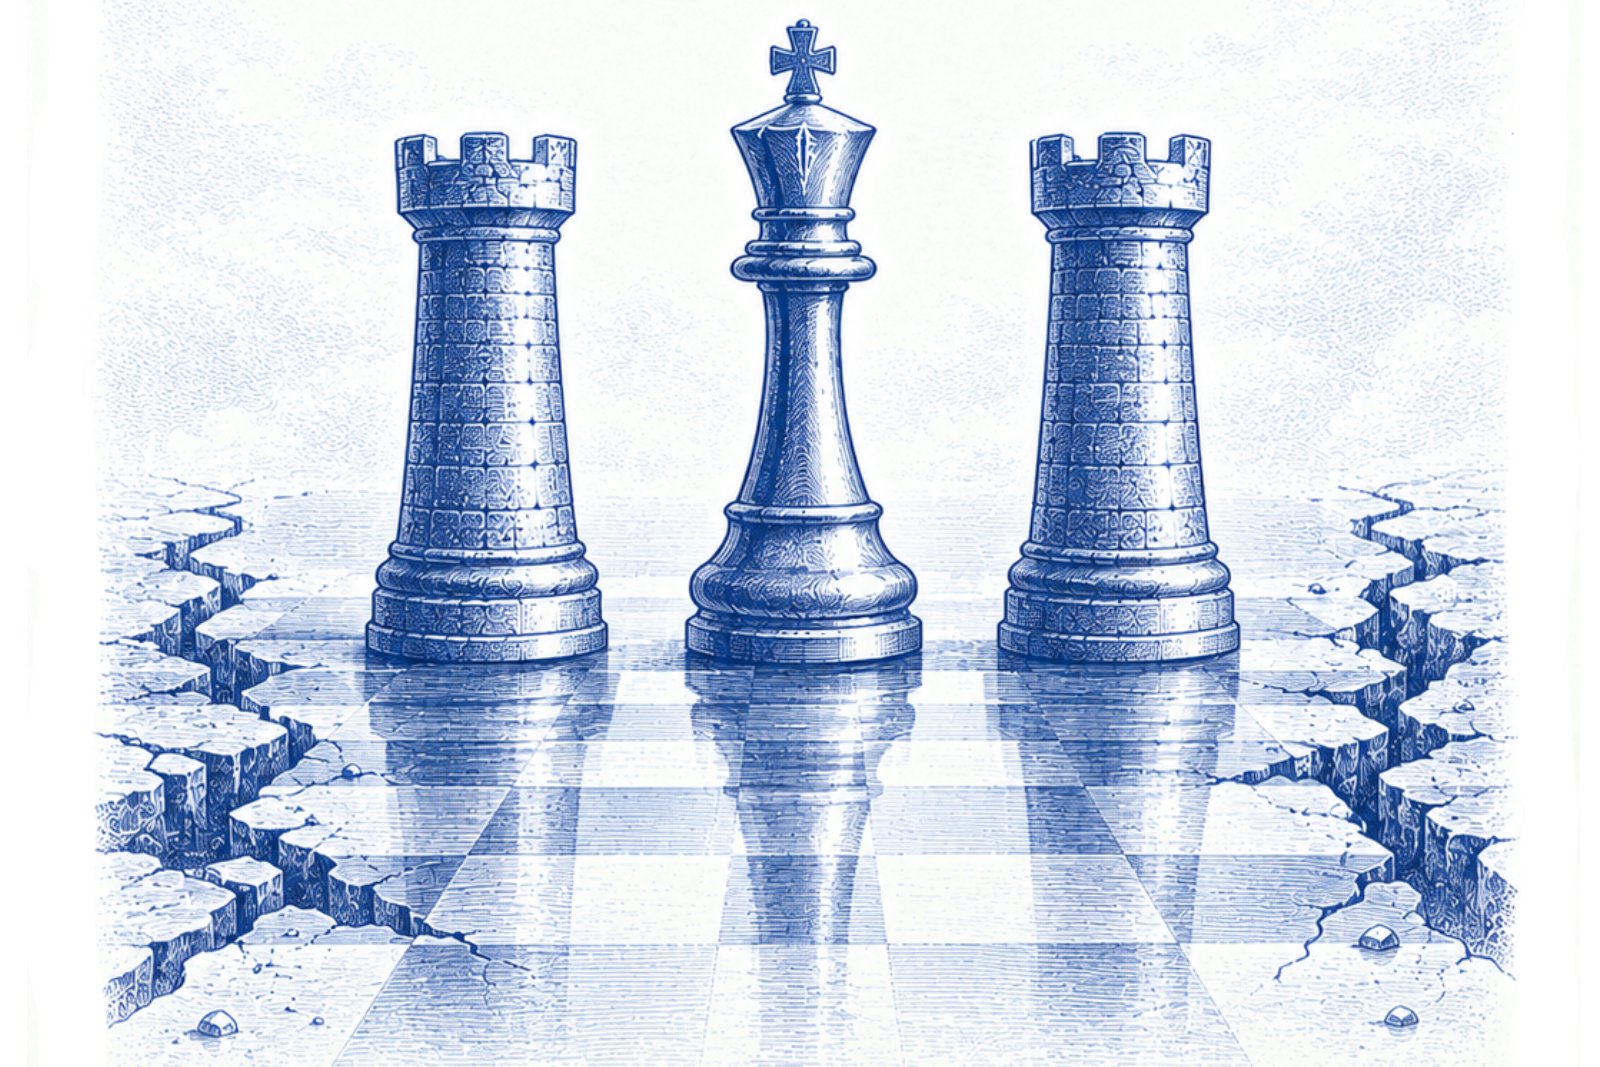
Picture a king standing between two columns of his own commissioning, precisely set and exactly measured, who reads their exactness as proof that he knows where his kingdom ends. His own surveyors built those columns, to his own specifications, and checked the measurements twice, so his confidence has real grounds, even if those grounds do not extend as far as he assumes. Standing where the architecture places him, he has no way of seeing the ground already opening in the territory beyond the columns, surveyed by no one, because nobody building a fence ever expects to need one quite that far out.
Leave a thought