

THE LIBRARY WITHOUT A CATALOGUE
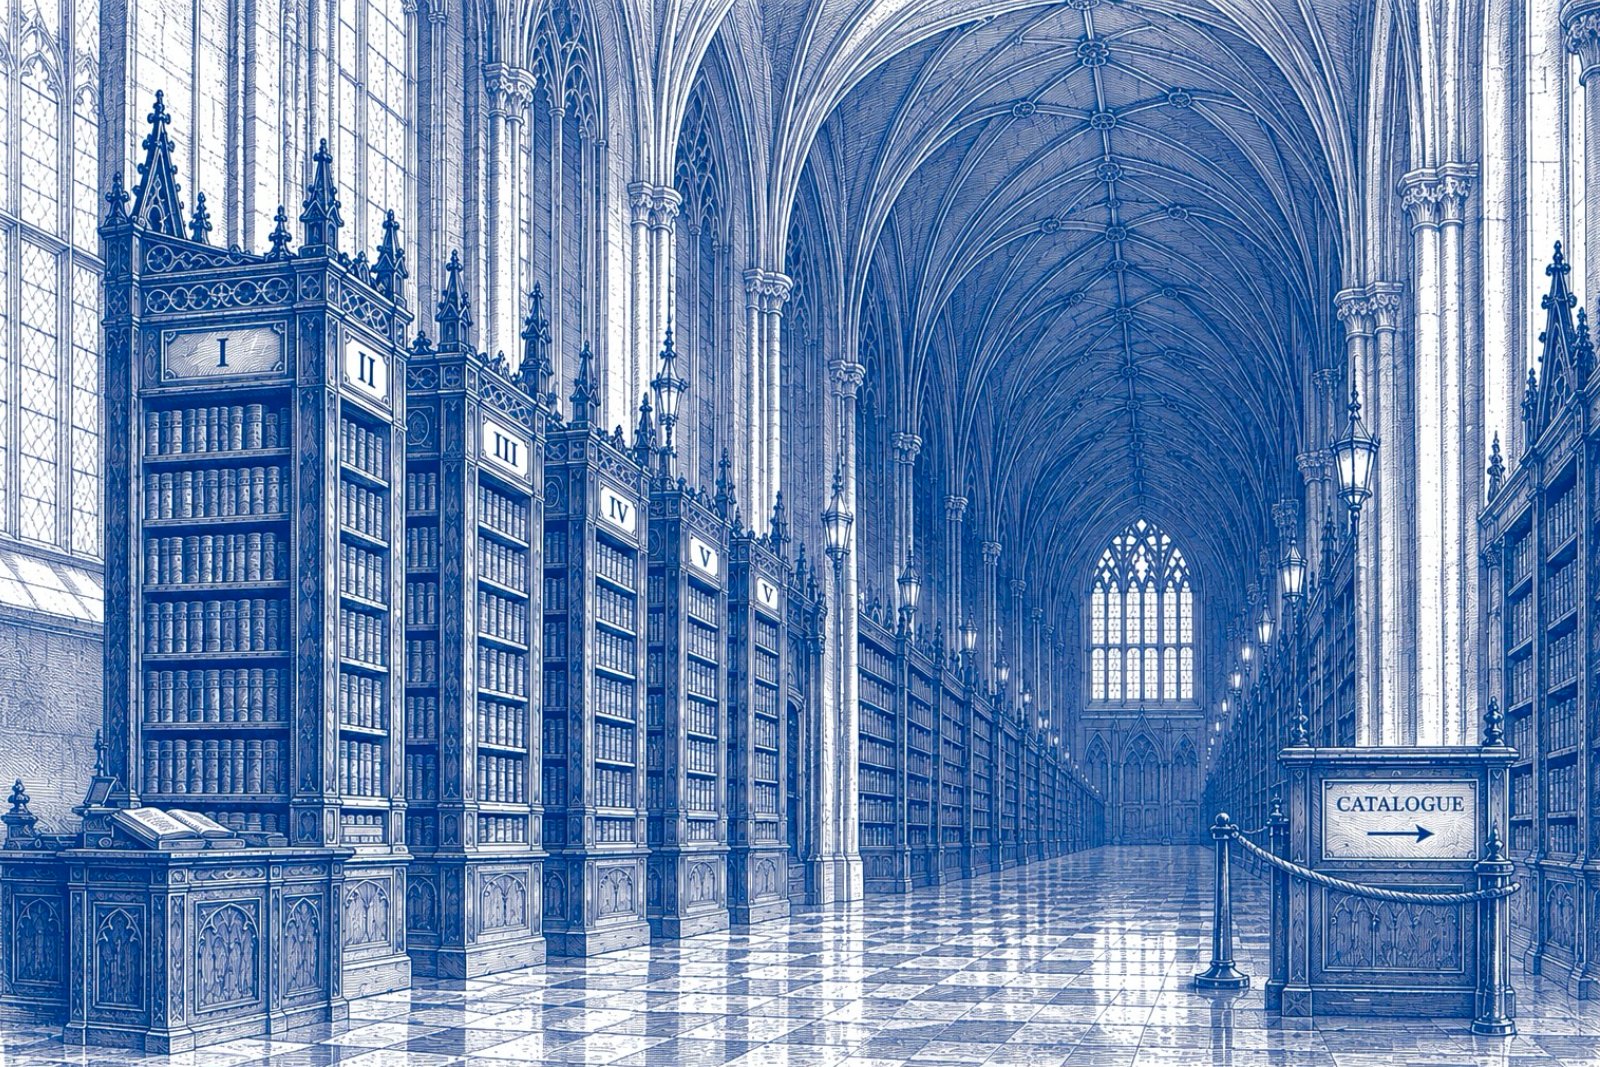
Jorge Luis Borges once dreamed up a library vast enough to hold every book that could ever be written: every combination of letters and spaces that could ever be arranged across four hundred and ten pages. Hidden somewhere among those infinite volumes is a flawless, word-for-word record of exactly how some particular company’s future will actually unfold. Shelved right beside it sit ten thousand plausible forgeries, equally fluent, equally confident, and wrong. Borges described the library’s architecture too: identical hexagonal galleries stretching upward and outward without any end that a librarian has ever found, every shelf holding books that are grammatically perfect and almost entirely meaningless.
The library’s cruelty is structural rather than accidental. Having the true volume on the shelf is worthless if nothing distinguishes it from the false ones beside it, and nothing does. Borges understood that possibility and knowledge are entirely different commodities, and that a library stocked with every possible truth offers only the first. A reader who wanders in looking for certainty finds instead an infinite catalogue of things that might be so.
A financial forecast is built inside a miniature version of exactly that library. Its early years occupy the well lit section near the entrance, where the shelves carry labels and a visitor can check what they say against something real. Current customers, signed contracts, known costs, a lease already paid for next year: these are verifiable facts, and a forecast built from them amounts to careful counting.
Walk further in and the lighting changes. Year six holds fewer verifiable facts than year three. Year nine holds fewer still, and year twelve is lit mainly by assumption: a growth rate chosen because it seems reasonable, a margin held steady because nobody has a better number, a competitor’s future behaviour assumed without much evidence either way. The spreadsheet keeps the same rows and the same arithmetic discipline all the way through, late years and early years alike, though the late years run less on evidence than on invention.
Something strange happens to the weight of all this arithmetic. In a typical discounted cash flow valuation, the years with the most evidence behind them, the near, well lit ones, usually contribute the smallest share of the final number. The years lit mainly by assumption, bundled together into what analysts call the terminal value, typically account for sixty to eighty per cent of the total. For a young, fast-growing company with little current revenue to anchor the early years, that share can run higher still, sometimes into the high eighties or nineties.
Take a company earning a modest hundred million dollars in free cash flow in its first forecast year, growing it steadily over a five year horizon, and discounting everything at a reasonable rate. Add up the five explicit years and they typically cover less than a third of the resulting valuation. The remaining share, in a case like this often around seventy per cent of the total, comes from a single number representing everything the business is assumed to earn after the explicit forecast simply stops.
Those mechanics behind a single terminal value figure are almost embarrassingly sensitive. A common method divides next year’s cash flow by the gap between the discount rate and an assumed rate of perpetual growth, a growth rate meant to hold, essentially forever, for a business that has not existed for more than a few years. Narrow that gap by a single percentage point, tightening the assumed long-run growth rate by not very much at all, and the terminal value can jump by twenty or thirty per cent. The entire valuation, in other words, can swing substantially on a decimal that nobody could defend with real evidence even if pressed directly.
Serious practitioners try to compensate by showing a spread of several terminal values, calculated across a range of plausible growth and discount rates and laid out in a small grid, so a reader can see how much the final number moves as the deep assumptions move. This is honest practice, and it helps. It does not change the underlying fact that the grid itself is still describing the same unlit shelves, only with the admission, printed in the open, that nobody is entirely sure which row of the grid is the right one.
This imbalance follows from simple mathematics: discounting combined with an assumption, built into nearly every such model, that a business keeps generating cash well beyond the years anyone bothered to forecast individually. Compress a near-infinite stream of future cash into one number, and that number will always dwarf a handful of near-term years, however carefully those years were built. The mathematics explains the imbalance on its own, without needing to blame anyone’s modelling choices; extra diligence spent on years one through five will never change where the weight of the valuation actually sits.
Not every business keeps the same share of itself in the dark. A mature, cash-generative company with a long trading history typically sees its terminal value settle lower, often in the range of fifty to sixty five per cent, because its near years are already doing real work. A young company with little revenue yet, a clinical-stage biotechnology firm hoping a drug eventually gets approved, can see the figure climb into the high eighties or nineties, which means the entire valuation rests on a handful of assumptions about a decade that has not started.
Amazon’s own history offers a famous illustration of a market willing to live inside the library’s dim shelves for years at a time. Through much of the 1990s and 2000s the company ran at a loss or close to it while its share price already implied enormous future profitability, profitability that had not yet arrived and that plenty of contemporary critics doubted would ever arrive at all. The near years were genuinely unprofitable, exactly as reported. The market’s confidence sat almost entirely in shelves far deeper in the stacks than any quarterly result could reach.
Courts asked to value a company in a shareholder dispute run into the same problem from a different angle. Expert witnesses on each side routinely agree on most of the explicit forecast years and then diverge sharply on the terminal growth assumption, because that is the one number large enough, and vague enough, to move the overall figure by the margin either side needs. The quarrel judges end up adjudicating is really about the unlit shelves, however much the arithmetic dominates the hearing. Once the inputs are fixed, the arithmetic is usually simple enough that nobody bothers to argue about it. The growth rate fed into that arithmetic is a different matter, hidden inside a single input cell that looks exactly as authoritative as every other cell around it.
All of which returns us to the library. Near its entrance, a person is doing something that deserves to be called counting: checking contracts, verifying costs, confirming that the lease has in fact been signed. Further back in the stacks, that same person has switched to something that deserves a different name: imagining, composing a plausible future out of a growth rate and a discount rate and very little else, dressed in the same rows and the same decimal points that made the entrance feel so solid. The catalogue, the part of the library anyone can actually check, runs out long before the shelves do.
Capital still has to be allocated across decades, however little anyone can verify about year twelve, and refusing to forecast only replaces one kind of guess with a different, less disciplined kind. The honest version of long range forecasting involves knowing, sentence by sentence, which part of the model a given number actually came from, and saying so plainly, since the uniform formatting of a spreadsheet otherwise implies a uniform confidence that the underlying years do not share.
Good analysts keep reading past the point where the catalogue’s labels run out, because refusing to think about year eight helps nobody raising money or allocating it. Such analysts owe the reader one simple thing: naming which shelf in the library a given figure was taken from, before asking anyone to trust it. The first five years of a model are accounting. The years after that borrow the same rows, the same decimals and the same confident tone, to describe a future nobody has any real evidence for yet. A reader who cannot tell the difference is trusting a number without knowing what kind of number it actually is. Year five, in most such models, is roughly where the catalogue ends and the honest guessing begins, which is as good a place as any to remember which kind of reading you are doing.
Leave a thought